

EAS 16931-14:2026
(Main)Electronic invoicing - Part 14: Examples to support the implementation of EN 16931-1
- Abstract
The document shall contain examples that are relevant for the implementation of the EN16931-1.
At least basic scenarios described in the EN16931-1 shall be documented but not limited to those scenarios.
Specific more complex scenarios can be documented as well.
Examples can be documented by means of a full invoice content or a snippet of an invoice.
- Status
- Published
- Publication Date
- 04-Aug-2026
- Technical Committee
- CEN/TC 434 - Project Committee - Electronic Invoicing
- Drafting Committee
- CEN/TC 434/WG 5 - Syntax bindings
- Current Stage
- 6060 - Definitive text made available (DAV) - Publishing
- Start Date
- 05-Aug-2026
- Due Date
- 01-Feb-2027
- Completion Date
- 05-Aug-2026
EAS 16931-14:2026 is a CEN European Agile Specification with examples for implementing EN 16931-1. It shows how common and more complex electronic invoice cases are expressed as full invoice content or snippets, with human-readable views and syntax representations in UBL and CII. It is aimed at people building, testing, checking, or mapping EN 16931-1 compliant invoicing systems.
What does EAS 16931-14:2026 specify?
EAS 16931-14:2026 specifies example electronic invoices that are relevant to the implementation of EN 16931-1. The examples cover basic scenarios described in EN 16931-1 and also more complex business cases, so the document is useful both for first implementations and for edge-case testing.
EAS 16931-14:2026 is organized into:
- Clause 1 Scope
- Clause 2 Normative references
- Clause 3 Terms and definitions
- Clause 4 Calculation examples, with 15 worked examples
- Bibliography
Clause 4 presents each example with a description and, where shown, syntax representations in UBL and CII. The examples are meant to be read alongside the invoice model in EN 16931-1, not as a separate invoicing rulebook.
What are the key requirements of EAS 16931-14:2026?
EAS 16931-14:2026 is mainly an example document, but it still sets out the calculation logic and usage patterns that implementations need to reproduce. The key practical message is that systems should calculate, round, and map invoice data the same way the examples do.
Invoice line calculations
Clause 4.1 gives the calculation rule used throughout the examples: invoice line net amount is calculated from item net price, item price base quantity, invoiced quantity, plus same-line charges and minus same-line allowances, with rounding half up to two decimals. Clause 4.1 also states that if item price base quantity is not stated, it is assumed to be 1, and that item net price equals item gross price minus item price discount.
In practice, this is the core rule for ERP, billing, and validation software. If the line calculation is wrong, the invoice total, VAT breakdown, and payable amount will also be wrong.
VAT rate, quantity, and unit cases
Clauses 4.2, 4.3, 4.4, 4.6, 4.7, 4.8, 4.9, and 4.10 show invoice lines with different VAT rates, item price base quantities, different units of measure, negative quantities, prepayment, exempt lines, reverse charge, and rounding differences. These examples show that EN 16931-1 supports mixed invoice structures, not just a single VAT rate and simple quantity pattern.
For implementers, this means a system must handle line-by-line unit codes, VAT category codes, negative lines for credits, and document-level totals that still reconcile correctly.
Discounts, allowances, and charges
Clauses 4.5 and 4.12 show discounts, allowances, and charges at both line level and document level. The examples distinguish between price discount inside the item price details and separate invoice line allowances or charges, and they also show document level allowances and charges that affect totals and VAT breakdown.
In practice, this matters because the same business discount can be represented in different ways depending on whether it belongs to the price, the line, or the document. Software needs to post the right amount in the right place, or tax totals will not match.
Taxes other than VAT
Clause 4.11 shows how taxes other than VAT can be represented. One example uses a separate invoice line for a tax on greenhouse-effect fluorinated gases, and another uses a document level charge for excise duty that does not take part in VAT taxable amount calculations.
This matters for businesses dealing with environmental taxes or excise duties, because the tax can be modeled as either a separate line or a charge, and the VAT treatment must follow the scenario shown in the example.
Payment, factoring, and corrections
Clauses 4.13, 4.14, and 4.15 cover factoring, payment instructions, and invoice corrections. The factoring example shows the invoice note, the identification of the factor as Payee, and the bank account used in favour of the factor. Clause 4.14 gives examples for SEPA credit transfer, non-SEPA transfer with branch identifiers and BIC, payment card, direct debit, and payment service provider. Clause 4.15 explains how supplementary invoices, credit notes, negative invoices, and replacement invoices are used when an invoice needs to be corrected.
For users, these clauses show how to carry payment data and correction references in a way that remains compatible with EN 16931-1 and with downstream payment or dispute handling.
Rounding at document level
Clauses 4.10 and 4.16 highlight rounding problems that can appear when line totals, VAT totals, VAT-inclusive prices, or prices with more than two decimals are involved. The examples show that line-level rounding and document-level rounding can produce different VAT totals if the calculation path is not controlled.
This is important for integration testing. A system should be checked with these cases before go-live, especially where totals must match exactly across invoice, tax reporting, and payment.
What terms does EAS 16931-14:2026 define?
EAS 16931-14:2026 uses the terms and definitions from EN 16931-1:2026. The examples also make several operational terms especially important.
- Invoice line net amount (BT-131) - the amount for one invoice line after applying quantity, unit price, line charges, and line allowances, with rounding used as shown in Clause 4.1.
- Item price base quantity (BT-149) - the quantity unit against which the item net price is stated, which defaults to 1 when not given.
- Document level allowance (BT-92) - an allowance that applies to the invoice as a whole and reduces the document totals.
- Document level charge (BT-99) - a charge that applies to the invoice as a whole and increases the document totals.
- Prepaid amount (BT-113) - an amount already paid before the invoice is settled, used in the prepayment example to derive a negative amount due.
- Reverse charge - a VAT category used in the examples for intracommunity supply, where the tax amount is 0 and the exemption text identifies the reason.
- Factoring - the assignment of an invoice to a factor, with the factor shown as the Payee and the payment account changed accordingly.
- UBL - the invoice examples shown in UBL syntax, based on ISO/IEC 19845 and the CEN syntax binding used in the series.
- CII - the invoice examples shown in UN/CEFACT XML Industry Invoice syntax.
Who uses EAS 16931-14:2026?
EAS 16931-14:2026 is used by software developers, ERP and accounting system integrators, testing teams, and implementation consultants who need to produce or validate invoices against EN 16931-1. It is also useful for quality managers, buyers, and finance teams who need to check whether an invoicing solution handles VAT, allowances, charges, payment data, and corrections the way the standard expects.
The examples are relevant across commercial trade, office applications, and public procurement because the document is about electronic invoicing for goods, works, and services, including mixed VAT cases, factoring, and payment scenarios.
What changed in EAS 16931-14:2026 from the previous edition?
EAS 16931-14:2026 supersedes the examples listed in EN 16931-1:2017+A1:2019, Annex A.
Which standards are used with EAS 16931-14:2026?
| Standard | What it contributes |
|---|---|
| EN 16931-1:2026 | The core semantic data model that the examples implement and whose terms and definitions apply. |
| CEN/TS 16931-3-2:2020 | The UBL syntax binding used for the UBL representations shown in the examples. |
| CEN/TS 16931-3-3:2020 | The CII syntax binding used for the CII representations shown in the examples. |
| ISO/IEC 19845 | The underlying UBL 2.1 syntax referenced for the UBL examples. |
| UN/CEFACT XML Industry Invoice D16B | The underlying invoice syntax referenced for the CII examples. |
What does the EAS 16931-14:2026 document contain?
EAS 16931-14:2026 contains worked invoice examples, calculation tables, and syntax snippets that show how the EN 16931-1 data model is used in practice. Clause 4 includes examples for VAT rate differences, price base quantity, unit of measure, discounts and allowances, negative lines, prepayments, exempt and reverse-charge cases, rounding, non-VAT taxes, factoring, payment instructions, corrections, and VAT-inclusive rounding issues.
Several examples include both a description and a human-readable visualization, then the same invoice information in UBL and CII syntax. That makes the document useful for mapping, implementation testing, and checking that totals, VAT breakdowns, and payment data all line up across business documents and XML output.
Relations
- Effective Date
- 25-Aug-2026
Get Certified
Connect with accredited certification bodies for this standard

BSI Group
BSI (British Standards Institution) is the business standards company that helps organizations make excellence a habit.
NYCE
Mexican standards and certification body.
Sponsored listings
Frequently Asked Questions
EAS 16931-14:2026 is a technical specification published by the European Committee for Standardization (CEN). Its full title is "Electronic invoicing - Part 14: Examples to support the implementation of EN 16931-1". This standard covers: The document shall contain examples that are relevant for the implementation of the EN16931-1. At least basic scenarios described in the EN16931-1 shall be documented but not limited to those scenarios. Specific more complex scenarios can be documented as well. Examples can be documented by means of a full invoice content or a snippet of an invoice.
The document shall contain examples that are relevant for the implementation of the EN16931-1. At least basic scenarios described in the EN16931-1 shall be documented but not limited to those scenarios. Specific more complex scenarios can be documented as well. Examples can be documented by means of a full invoice content or a snippet of an invoice.
EAS 16931-14:2026 is classified under the following ICS (International Classification for Standards) categories: 35.240.20 - IT applications in office work; 35.240.63 - IT applications in trade. The ICS classification helps identify the subject area and facilitates finding related standards.
EAS 16931-14:2026 has the following relationships with other standards: It is inter standard links to EN 16931-1:2026. Understanding these relationships helps ensure you are using the most current and applicable version of the standard.
EAS 16931-14:2026 is associated with the following European legislation: EU Directives/Regulations: 2014/55/EU. When a standard is cited in the Official Journal of the European Union, products manufactured in conformity with it benefit from a presumption of conformity with the essential requirements of the corresponding EU directive or regulation.
EAS 16931-14:2026 is available in PDF format for immediate download after purchase. The document can be added to your cart and obtained through the secure checkout process. Digital delivery ensures instant access to the complete standard document.
Standards Content (Sample)
SLOVENSKI STANDARD
01-november-2026
Elektronsko izdajanje računov - 14. del: Primeri za podporo izvajanju EN 16931-1
Electronic invoicing - Part 14: Examples to support the implementation of EN 16931-1
Elektronische Rechnungsstellung - Teil 14: Beispiele zur Unterstützung der Umsetzung
der EN 16931-1
Facturation électronique - Partie 14 : Exemples visant à faciliter la mise en œuvre de
l'EN 16931-1
Ta slovenski standard je istoveten z: EAS 16931-14:2026
ICS:
03.100.20 Trgovina. Komercialna Trade. Commercial function.
dejavnost. Trženje Marketing
35.240.20 Uporabniške rešitve IT pri IT applications in office work
pisarniškem delu
35.240.63 Uporabniške rešitve IT v IT applications in trade
trgovini
2003-01.Slovenski inštitut za standardizacijo. Razmnoževanje celote ali delov tega standarda ni dovoljeno.
EUROPEAN AGILE SPECIFICATION EAS 16931-14
SPÉCIFICATION AGILE EUROPÉENNE
EUROPÄISCHE AGILE SPEZIFIKATION
August 2026
ICS 35.240.20; 35.240.63
English Version
Electronic invoicing - Part 14: Examples to support the
implementation of EN 16931-1
Facturation électronique - Partie 14 : Exemples visant à Elektronische Rechnungsstellung - Teil 14: Beispiele
faciliter la mise en œuvre de l'EN 16931-1 zur Unterstützung der Umsetzung der EN 16931-1
This European Agile Specification (EAS) was approved by CEN on 15 July 2026 for application.
The period of validity of this EAS is limited initially to three years.
CEN members are required to announce the existence of this EAS in the same way as for an EN and to make the EAS available
promptly at national level in an appropriate form. It is permissible to keep conflicting national standards in force (in parallel to
the EAS.
CEN members are the national standards bodies of Austria, Belgium, Bulgaria, Croatia, Cyprus, Czech Republic, Denmark, Estonia,
Finland, France, Germany, Greece, Hungary, Iceland, Ireland, Italy, Latvia, Lithuania, Luxembourg, Malta, Netherlands, Norway,
Poland, Portugal, Republic of North Macedonia, Romania, Serbia, Slovakia, Slovenia, Spain, Sweden, Switzerland, Türkiye and
United Kingdom.
EUROPEAN COMMITTEE FOR STANDARDIZATION
COMITÉ EUROPÉEN DE NORMALISATIO N
EUROPÄISCHES KOMITEE FÜR NORMUN G
CEN-CENELEC Management Centre: Rue de la Science 23, B-1040 Brussels
© 2026 CEN All rights of exploitation in any form and by any means reserved Ref. No. EAS 16931-14:2026 E
worldwide for CEN national Members.
Page
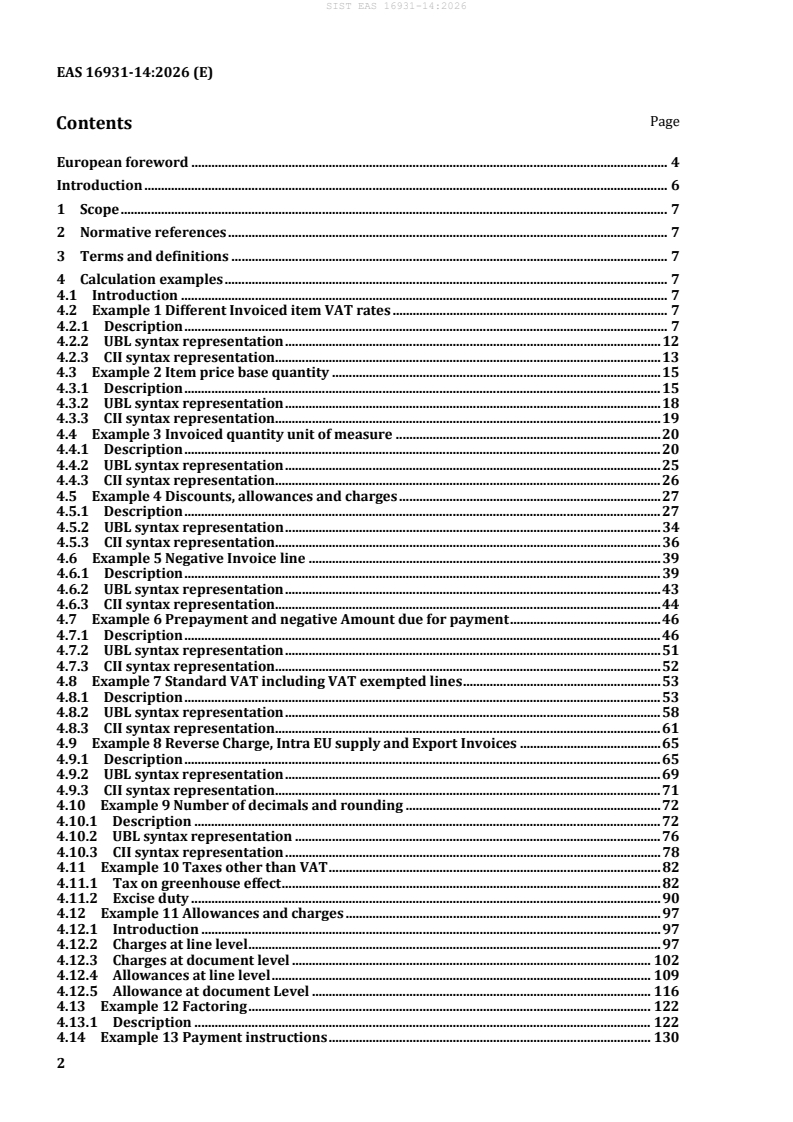
Contents
European foreword . 4
Introduction . 6
1 Scope . 7
2 Normative references . 7
3 Terms and definitions . 7
4 Calculation examples . 7
4.1 Introduction . 7
4.2 Example 1 Different Invoiced item VAT rates . 7
4.2.1 Description . 7
4.2.2 UBL syntax representation . 12
4.2.3 CII syntax representation . 13
4.3 Example 2 Item price base quantity . 15
4.3.1 Description . 15
4.3.2 UBL syntax representation . 18
4.3.3 CII syntax representation . 19
4.4 Example 3 Invoiced quantity unit of measure . 20
4.4.1 Description . 20
4.4.2 UBL syntax representation . 25
4.4.3 CII syntax representation . 26
4.5 Example 4 Discounts, allowances and charges . 27
4.5.1 Description . 27
4.5.2 UBL syntax representation . 34
4.5.3 CII syntax representation . 36
4.6 Example 5 Negative Invoice line . 39
4.6.1 Description . 39
4.6.2 UBL syntax representation . 43
4.6.3 CII syntax representation . 44
4.7 Example 6 Prepayment and negative Amount due for payment . 46
4.7.1 Description . 46
4.7.2 UBL syntax representation . 51
4.7.3 CII syntax representation . 52
4.8 Example 7 Standard VAT including VAT exempted lines . 53
4.8.1 Description . 53
4.8.2 UBL syntax representation . 58
4.8.3 CII syntax representation . 61
4.9 Example 8 Reverse Charge, Intra EU supply and Export Invoices . 65
4.9.1 Description . 65
4.9.2 UBL syntax representation . 69
4.9.3 CII syntax representation . 71
4.10 Example 9 Number of decimals and rounding . 72
4.10.1 Description . 72
4.10.2 UBL syntax representation . 76
4.10.3 CII syntax representation . 78
4.11 Example 10 Taxes other than VAT . 82
4.11.1 Tax on greenhouse effect . 82
4.11.2 Excise duty . 90
4.12 Example 11 Allowances and charges . 97
4.12.1 Introduction . 97
4.12.2 Charges at line level . 97
4.12.3 Charges at document level . 102
4.12.4 Allowances at line level . 109
4.12.5 Allowance at document Level . 116
4.13 Example 12 Factoring . 122
4.13.1 Description . 122
4.14 Example 13 Payment instructions . 130
4.14.1 Introduction .130
4.14.2 SEPA bank transfer .131
4.14.3 Non SEPA transfer using branch identifiers and BIC code .135
4.14.4 Payment card .139
4.14.5 Direct debit .143
4.14.6 Paid by a payment service provider .147
4.15 Example 14 Corrections .152
4.15.1 Description .152
4.16 Example 15 Rounding issues due to VAT-inclusive prices or prices with more
than 2 decimals .153
4.16.1 Description .153
4.16.2 UBL syntax representation .156
4.16.3 CII syntax representation .158
Bibliography .165
European foreword
This document (EAS 16931-14:2026) has been prepared by Technical Committee CEN/TC 434
“Electronic Invoicing”, the secretariat of which is held by NEN.
Attention is drawn to the possibility that some of the elements of this document may be the subject of
patent rights. CEN shall not be held responsible for identifying any or all such patent rights.
This document supersedes the examples listed in EN 16931-1:2017+A1:2019 [1], Annex A.
This document is part of a set of documents, consisting of:
— EN 16931-1 [2], Electronic invoicing - Part 1: Semantic data model of the core elements of an
electronic invoice
— CEN/TS 16931-2 [3], Electronic invoicing - Part 2: List of syntaxes that comply with EN 16931-1
— CEN/TS 16931-3-1 [4], Electronic invoicing - Part 3-1: Methodology for syntax bindings of the
core elements of an electronic invoice
— CEN/TS 16931-3-2 [5], Electronic invoicing - Part 3-2: Syntax binding for ISO/IEC 19845 (UBL
2.1) invoice and credit note
— CEN/TS 16931-3-3 [6], Electronic invoicing - Part 3-3: Syntax binding for UN/CEFACT XML
Industry Invoice D16B
— CEN/TS 16931-3-4 [7], Electronic invoicing - Part 3-4: Syntax binding for UN/EDIFACT INVOIC
D16B
— CEN/TR 16931-4 [8], Electronic invoicing - Part 4: Guidelines on interoperability of electronic
invoices at the transmission level
— CEN/TS 16931-5 [9], Electronic invoicing - Part 5: Guidelines on the use of sector or country
extensions in conjunction with EN 16931-1, methodology to be applied in the real environment
— CEN/TR 16931-6 [10], Electronic invoicing - Part 6: Result of the test of EN 16931-1 with respect
to its practical application for an end user
— CEN/TS 16931-7 [11], Electronic invoicing - Part 7: Methodology for the development and use of
EN 16931-1 compliant structured Core Invoice Usage Specifications
— CEN/TS 16931-8 [12], Electronic invoicing - Part 8: Semantic data model of the elements of an e-
receipt or a simplified electronic invoice
— CEN/TR 16931-9 [13], Electronic invoicing - Part 9: VAT reporting and gap analysis with current
eInvoicing standardization deliverables
— CEN/TR 16931-10 [14], Electronic invoicing - Part 10: Additional requirements to extend to B2B
— FprCEN/TS 16931-11-2 [15], Electronic invoicing - Part 11-2: Syntax binding of CEN/TS 16931-8
to ISO/IEC 19845 (UBL)
— FprCEN/TS 16931-11-3 [16], Electronic invoicing - Part 11-3: Syntax binding of CEN/TS 16931-8
to UN/CEFACT XML Industry Invoice
— FprCEN/TR 16931-12 [17], Electronic invoicing - Part 12: Study on the internationalization of EN
16931-1
— CEN/TS 16931-13 [18], Electronic invoicing - Part 13: Functional specification and guidance for
the eInvoice Registry of CIUS and Extensions
Any feedback and questions on this document should be directed to the users’ national standards body.
A complete listing of these bodies can be found on the CEN website.
According to the CEN/CENELEC Internal Regulations, the national standards organisations of the
following countries are bound to announce this European Agile Specification: Austria, Belgium, Bulgaria,
Croatia, Cyprus, Czech Republic, Denmark, Estonia, Finland, France, Germany, Greece, Hungary, Iceland,
Ireland, Italy, Latvia, Lithuania, Luxembourg, Malta, Netherlands, Norway, Poland, Portugal, Republic of
North Macedonia, Romania, Serbia, Slovakia, Slovenia, Spain, Sweden, Switzerland, Türkiye and the
United Kingdom.
Introduction
The European Commission estimates that “The mass adoption of e-invoicing within the EU would lead
to significant economic benefits and it is estimated that moving from paper to Electronic invoices will
generate savings of around EUR 240 billion over a six-year period” . Based on this recognition “The
Commission wanted to see e-invoicing become the predominant method of invoicing by 2020 in
Europe”.
To achieve this goal, Directive 2014/55/EU on electronic invoicing in public procurement aims at
facilitating the use of Electronic invoices by economic operators when supplying goods, works and
services to the public administration. The Directive sets out the legal framework for the establishment
and use of a European Standard (EN 16931-1:2026 [19]) for the Semantic data model of the Core
Elements of an Electronic invoice.
In 2025, the EC also proposes to amend Council Directive 2006/112/EC (the VAT directive) in order to
introduce a new method of VAT reporting for intra community trade. This method is based on electronic
invoicing, conformant to EN 16931-1:2026 [19].
In order to guide implementations of electronic invoicing systems that conform to EN 16931-1:2026
[19], this document (EAS 16931-14) contains examples of electronic invoices for various business
environments. The electronic invoices in these examples conform to EN 16931-1:2026 [19]. These
examples include syntax representations in UBL (ISO/IEC 19845 [20] invoice and credit note, according
to CEN/TS 16931-3-2:2020 [21] and CII (UN/CEFACT XML Industry Invoice, according to CEN/TS
16931-3-3:2020 [22].
http://eur-lex.europa.eu/LexUriServ/LexUriServ.do?uri=COM:2010:0712:FIN:en:PDF
http://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX:02006L0112-20150101
1 Scope
This document contains examples that are relevant for the implementation of EN 16931-1 [2].
Basic scenarios described in the EN 16931-1 [2] are documented but not limited to those scenarios.
Specific more complex scenarios are documented as well.
Examples are documented by means of a full invoice content or a snippet of an invoice, together with a
human readable visualization and representation in two syntaxes: UBL (CEN/TS 16931-3-2:2020 [21])
and CII (CEN/TS 16931-3-3:2020 [22]).
2 Normative references
The following documents are referred to in the text in such a way that some or all of their content
constitutes requirements of this document. For dated references, only the edition cited applies. For
undated references, the latest edition of the referenced document (including any amendments) applies.
EN 16931-1:2026, Electronic invoicing - Part 1: Semantic data model of the core elements of an electronic
invoice
3 Terms and definitions
For the purposes of this document, the terms and definitions given in EN 16931-1:2026 apply.
ISO and IEC maintain terminology databases for use in standardization at the following addresses:
— ISO Online browsing platform: available at https://www.iso.org/obp
— IEC Electropedia: available at https://www.electropedia.org/
4 Calculation examples
4.1 Introduction
Calculation within an Invoice line is enforced in the validation:
— Invoice line net amount = Item net price / Item price base quantity x Invoiced quantity + ∑ Charge
amount (same line) - ∑ Allowance amount (same line), rounded “half up” to two decimals;
— If the Item price base quantity is not stated in an Invoice instance then it is assumed to be 1;
— Item net price = Item gross price - Item price discount.
The issuer of the Invoice can nevertheless expect the Buyer to verify quantities and prices against other
relevant information such as contracts and orders and to possibly dispute the Invoice with a business
level objection.
In the examples below, the calculation of the Invoice elements are illustrated in different common
scenarios.
4.2 Example 1 Different Invoiced item VAT rates
4.2.1 Description
In this example, 11 bottles of wine have been ordered. Five of the bottles are 12,00 EUR each exclusive
of VAT. See Table 1. The VAT is 25 %. The other 6 bottles are 15,00 EUR each exclusive of VAT but
invoiced as a case. The VAT rate is 12 %. These calculations are shown in Table 2. For visualization of
the invoice, see Figure 1 and Figure 2.
Table 1 — Invoice lines
Invoice Item name Invoiced Item net Invoiced Invoiced Invoiced Invoice
line quantity price quantity item VAT item VAT
line net
identifier unit of category rate amount
measure code
1 Wine- 5 12,00 Bottle Standard 25 60.00
bottles rate
2 Wine–case 1 90,00 Case Standard 12 90.00
of 6 rate
Table 2 — Calculations
BG/BT Business Term Name Value Remarks / Calculation
BG-25 INVOICE LINE 1
BT-129 Invoiced quantity: 5 EUR
BT-130 Invoiced quantity unit of Bottle
measure:
BT-146 Item net price: 12,00
BT-149 Item price base quantity: 1
BT-131 Invoice line net amount: 60,00 EUR, Invoiced quantity x
(Item net price/Item
price base quantity)
BT-151 Invoiced item VAT Standard rate
category code:
BT-152 Invoiced item VAT rate: 25 %
BG-25 INVOICE LINE 2
BT-129 Invoiced quantity: 1
BT-130 Invoiced quantity unit of Case
measure:
BT-146 Item net price: 90,00 EUR
BT-149 Item price base quantity: 1
BT-131 Invoice line net amount: 90,00 EUR, Invoiced quantity x
(Item net price/Item
price base quantity)
BT-151 Invoiced item VAT Standard rate
category code:
BT-152 Invoiced item VAT rate: 12
BG-23 VAT BREAKDOWN
BT-118 VAT category code: Standard rate
BT-119 VAT category rate: 25 %
BT-116 VAT category taxable 60,00 EUR, Sum of “Invoice line
amount: net amount” (where
“VAT Category code”
AND “VAT category rate”
matches line
BG/BT Business Term Name Value Remarks / Calculation
information) (see BR-S-
8)
BT-117 VAT category tax 15,00 EUR, “VAT category
amount: taxable amount” x (“VAT
category rate” / 100),
rounded to two decimals.
(See BR-CO-17).
BG-23 VAT BREAKDOWN
BT-118 VAT category code: Standard rate
BT-119 VAT category rate: 12 %
BT-116 VAT category taxable 90,00 EUR, Sum of “Invoice line
amount: net amount” (where
“VAT Category code”
AND “VAT category rate”
matches line
information) (see BR-S-
8)
BT-117 VAT category tax 10,80 EUR, “VAT category
amount: taxable amount” x (“VAT
category rate” / 100),
rounded to two decimals.
(See BR-CO-17)
BG-22 DOCUMENT TOTALS
BT-106 Sum of Invoice line net 150,00 EUR, Sum of “Invoice line
amount: net amount” (See BR-CO-
10)
BT-109 Invoice total amount 150,00 EUR, Sum of “Invoice line
without VAT: net amount” - Sum of
allowances on document
level + Sum of charges on
document level (see BR-
CO-13)
BT-110 Invoice total VAT 25,80 EUR, Sum of “VAT
amount: category tax amount”
(See BR-CO-14)
BT-112 Invoice total amount 175,80 EUR, “Invoice total
with VAT: amount without VAT” +
“Invoice total VAT
amount” (see BR-CO-15)
BT-115 Amount due for 175,80 EUR, “Invoice total VAT
payment: amount” - “Paid amount”
+ “Rounding amount”
(see BR-CO-16)
Figure 1 — Example 1 invoice visualization page 1
Figure 2 — Example 1 invoice visualization page 2
4.2.2 UBL syntax representation
25.80
60.00
15.00
S
25.0
VAT
90.00
10.80
S
12.0
VAT
currencyID="EUR">150.00
currencyID="EUR">150.00
currencyID="EUR">175.80
175.80
1
5.0
currencyID="EUR">60.00
Wine-bottle
S
25.0
VAT
12.00
2
1.0
currencyID="EUR">90.00
Wine-case of 6
S
12.0
VAT
90.00
4.2.3 CII syntax representation
xmlns:qdt="urn:un:unece:uncefact:data:standard:QualifiedDataType:100"
xmlns:udt="urn:un:unece:uncefact:data:standard:UnqualifiedDataType:100"
xmlns:rsm="urn:un:unece:uncefact:data:standard:CrossIndustryInvoice:100"
xmlns:ram="urn:un:unece:uncefact:data:standard:ReusableAggregateBusiness
InformationEntity:100">
urn:cen.eu:en16931:2026
...
1
1101
Wine - Bottle
12.00
5
VAT
S
25
60.00
2
1102
Wine-Case of 6
90.00
1
VAT
S
12
90.00
...
...
EUR
10.80
VAT
90.00
S
12
15.00
VAT
60.00
S
25
150.00
150.00
25.80
175.80
175.80
4.3 Example 2 Item price base quantity
4.3.1 Description
In this example, 10 000 screws are invoiced. See Table 3. Due to the low unit price, they are invoiced per
1 000 pieces. The price for one screw is EUR 0,0045 exclusive of VAT. The VAT rate is 25 %. This
calculation is shown in Table 4. A visualization of this invoice is in Figure 3 and Figure 4.
Table 3 — Invoice lines
Invoice Item Invoiced Item Item Invoiced Invoiced Invoiced Invoice
line name quantity net price quantity item item line net
identifier price base unit of VAT VAT amount
quantity measure category rate
code
1 screw 10 000 4,50 1 000 Piece Standard 25 45,00
rate
Table 4 — Calculations
BG/BT Business Term Name Value Remarks / Calculation
BG-25 INVOICE LINE 1
BT-129 Invoiced quantity: 10 000 Pieces
BT-130 Invoiced quantity unit of Piece
measure:
BT-146 Item net price: 4,50 EUR
BT-149 Item price base quantity: 1 000 Pieces
BT-131 Invoice line net amount: 45,00 EUR, Invoiced quantity x
(Item net price/Item
price base quantity)
BT-151 Invoiced item VAT Standard rate
category code:
BT-152 Invoiced item VAT rate: 25 %
Figure 3
Figure 4
4.3.2 UBL syntax representation
xmlns:cac="urn:oasis:names:specification:ubl:schema:xsd:CommonAggregateC
omponents-2"
xmlns:cbc="urn:oasis:names:specification:ubl:schema:xsd:CommonBasicCompo
nents-2"
xmlns="urn:oasis:names:specification:ubl:schema:xsd:Invoice-2">
urn:cen.eu:en16931:2017#compliant#urn:fdc:peppol.eu
:2017:poacc:billing:3.0
urn:fdc:peppol.eu:2017:poacc:billing:01:1.0
D>
V01/15000004
2026-04-09
2026-05-09
380
Testcase 6
EUR
YR127130
...
...
...
30 days after invoice date
11.25
45.00
11.25
S
25
VAT
currencyID="EUR">45
currencyID="EUR">45.00
currencyID="EUR">56.25
0.00
56.25
1
10000
currencyID="EUR">45
Screw
S
25
VAT
4.50
1000
4.3.3 CII syntax representation
xmlns:qdt="urn:un:unece:uncefact:data:standard:QualifiedDataType:100"
xmlns:udt="urn:un:unece:uncefact:data:standard:UnqualifiedDataType:100"
xmlns:rsm="urn:un:unece:uncefact:data:standard:CrossIndustryInvoice:100"
xmlns:ram="urn:un:unece:uncefact:data:standard:ReusableAggregateBusiness
InformationEntity:100">
urn:cen.eu:en16931:2026
...
1
1101
Screw
4.50
1000
10000
VAT
S
25
45.00
. . .
. . .
EUR
11.25
VAT
45.00
S
25
45.00
45.00
11.25
56.25
56.25
4.4 Example 3 Invoiced quantity unit of measure
4.4.1 Description
In this example, one chicken has been ordered, but the Invoice is in kilograms. See Table 5. In the Invoice
line both the quantity and the price refer to the same unit of measure and the relationship between the
order unit and the Invoice unit is not explicit. The Item net price is 9,50 EUR exclusive of VAT including
a 0,50 EUR discount. The VAT rate is 12,50 %. The calculation is shown in Table 6. A visualization of this
invoice is in Figure 5 and Figure 6.
Table 5 — Invoice lines
Invoice
Item Invoiced Item Item Item Invoiced Invoiced Invoiced Invoice
line name quantity net price gross quantity item item line net
identifier price discount price unit of VAT VAT amount
measure category rate
code
1 Chicken 1,3 9,50 0,50 10,00 Kilogram Standard 12,50 12,35
rate
Table 6 — Calculations
BG/BT Business Term Name Value Remarks / Calculation
BG-25 INVOICE LINE 1
BT-129 Invoiced quantity: 1,3 kg
BT-130 Invoiced quantity unit of Kilogram
measure:
BT-146 Item net price: 9,50 EUR, Item gross price –
Item price discount
BT-147 Item price discount: 0,50 EUR
BT-148 Item gross price: 10,00 EUR
BT-149 Item price base quantity: 1 kg
BT-131 Invoice line net amount: 12,35 EUR, Invoiced quantity x
(Item net price/Item
price base quantity)
BT-151 Invoiced item VAT Standard rate
category code:
BT-152 Invoiced item VAT rate: 25 %
BG-23 VAT BREAKDOWN
BT-118 VAT category code: Standard rate
BT-119 VAT category rate: 12,5 %
BT-116 VAT category taxable 12,35 EUR, Sum of “Invoice line
amount: net amount” (where
“VAT Category code”
AND “VAT category rate”
matches line
information) (See BR-S-
8)
BT-117 VAT category tax 1,54 EUR, “VAT category
amount: taxable amount” x (“VAT
category rate” / 100),
rounded to two decimals.
(See BR-CO-17)
BG-22 DOCUMENT TOTALS
BT-106 Sum of Invoice line net 12,35 EUR, Sum of “Invoice line
amount: net amount” (see BR-CO-
10)
BT-109 Invoice total amount 12,35 EUR, Sum of “Invoice line
without VAT: net amount” - Sum of
allowances on document
level + Sum of charges on
document level (see BR-
CO-13)
BT-110 Invoice total VAT 1,54 EUR, Sum of “VAT
amount: category tax amount”
(See BR-CO-14)
BT-112 Invoice total amount 13,89 EUR, “Invoice total
with VAT: amount without VAT” +
“Invoice total VAT
amount” (see BR-CO-15)
BG/BT Business Term Name Value Remarks / Calculation
BT-115 Amount due for 13,89 EUR, “Invoice total VAT
payment: amount” - “Paid amount”
(See BR-CO-16)
Figure 5
Figure 6
4.4.2 UBL syntax representation
xmlns:cac="urn:oasis:names:specification:ubl:schema:xsd:CommonAggregateC
omponents-2"
xmlns:cbc="urn:oasis:names:specification:ubl:schema:xsd:CommonBasicCompo
nents-2"
xmlns="urn:oasis:names:specification:ubl:schema:xsd:Invoice-2">
urn:cen.eu:en16931:2017#compliant#urn:fdc:peppol.eu
:2017:poacc:billing:3.0
urn:fdc:peppol.eu:2017:poacc:billing:01:1.0
D>
V01/15000004
2026-04-09
2026-05-09
380
Testcase 6
EUR
YR127130
...
...
...
30 days after invoice date
1.54
12.35
1.54
S
...